EURUSD
- EUR/USD Price: The EUR/USD pair is trading in negative territory below the 1.1200 level during early European trading on Friday.
- French bonds: France’s benchmark 10-year government bond yield rose by 6.5 basis points to 5.06%, after briefly reaching 5.1415%, its highest level since July 2002. Rising borrowing costs highlight mounting concerns over France’s public finances.
- Political outlook: Elias Haddad, senior markets strategist at Brown Brothers Harriman & Co., said political gridlock and public anger over the high cost of living are making it extremely difficult to repair France’s public finances ahead of next year’s presidential election.
- ECB rate: The European Central Bank is expected to keep its benchmark interest rate unchanged at 2.5% next week, although a rate hike before the end of the year is largely priced in, according to Reuters.
- Data ahead: The eurozone’s flash Purchasing Managers’ Index (PMI) readings for October are due for release and are expected to show stabilisation, with slight declines following improvements in recent months.
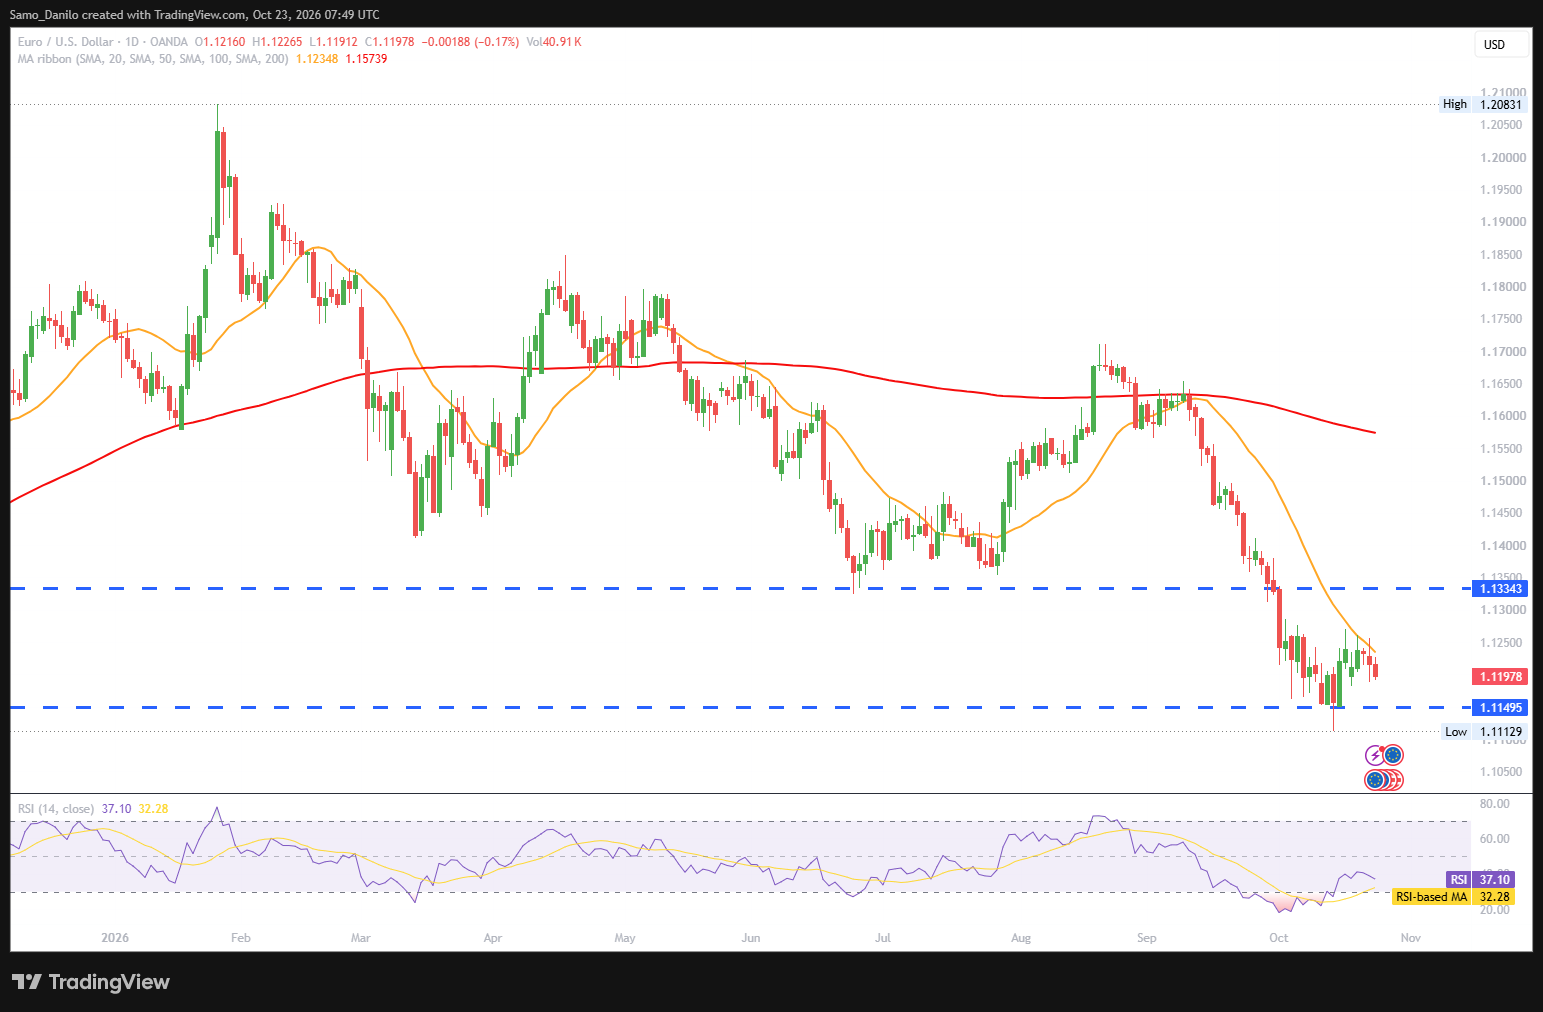
| SMA (20) | Falling |  | |
| RSI (14) | Slightly Falling | |
|
| MACD (12, 26, 9) | Slightly Falling | |
Closing statement: EUR/USD remains under pressure below 1.1200 as rising French borrowing costs and political gridlock weigh on sentiment toward the euro. Although expectations of an ECB rate hike before year-end could offer some support, the upcoming eurozone PMIs may prove decisive for the pair’s near-term direction. Weaker business activity data could extend the decline, while more resilient readings may encourage a recovery if they reinforce expectations of tighter ECB policy.
GBPUSD
- GBP/USD Price: The British Pound is trading slightly lower against the US Dollar on Friday, with GBP/USD hovering around 1.3390 despite disappointing UK retail sales data.
- Retail sales: UK retail sales declined by 0.4% in September, according to the Office for National Statistics, significantly exceeding the market’s forecast of a 0.1% decrease. However, August’s growth was revised upward to 0.7% from 0.5%, offering some reassurance that the latest decline follows a stronger previous month.
- BoE rate: The stronger-than-expected UK Consumer Price Index data released on Wednesday added to evidence of persistent inflationary pressures associated with elevated oil prices. This has strengthened expectations that the Bank of England may be forced to tighten monetary policy at its November 5 meeting.
- Consumer confidence: The UK GfK Consumer Confidence Index fell to -24 in October, significantly below the expected reading of -14 and reaching its lowest level since September 2024.
- Data ahead: The US S&P Global flash Purchasing Managers’ Index (PMI) readings for October are due for release, with investors assessing whether the strong business activity recorded in September has continued.
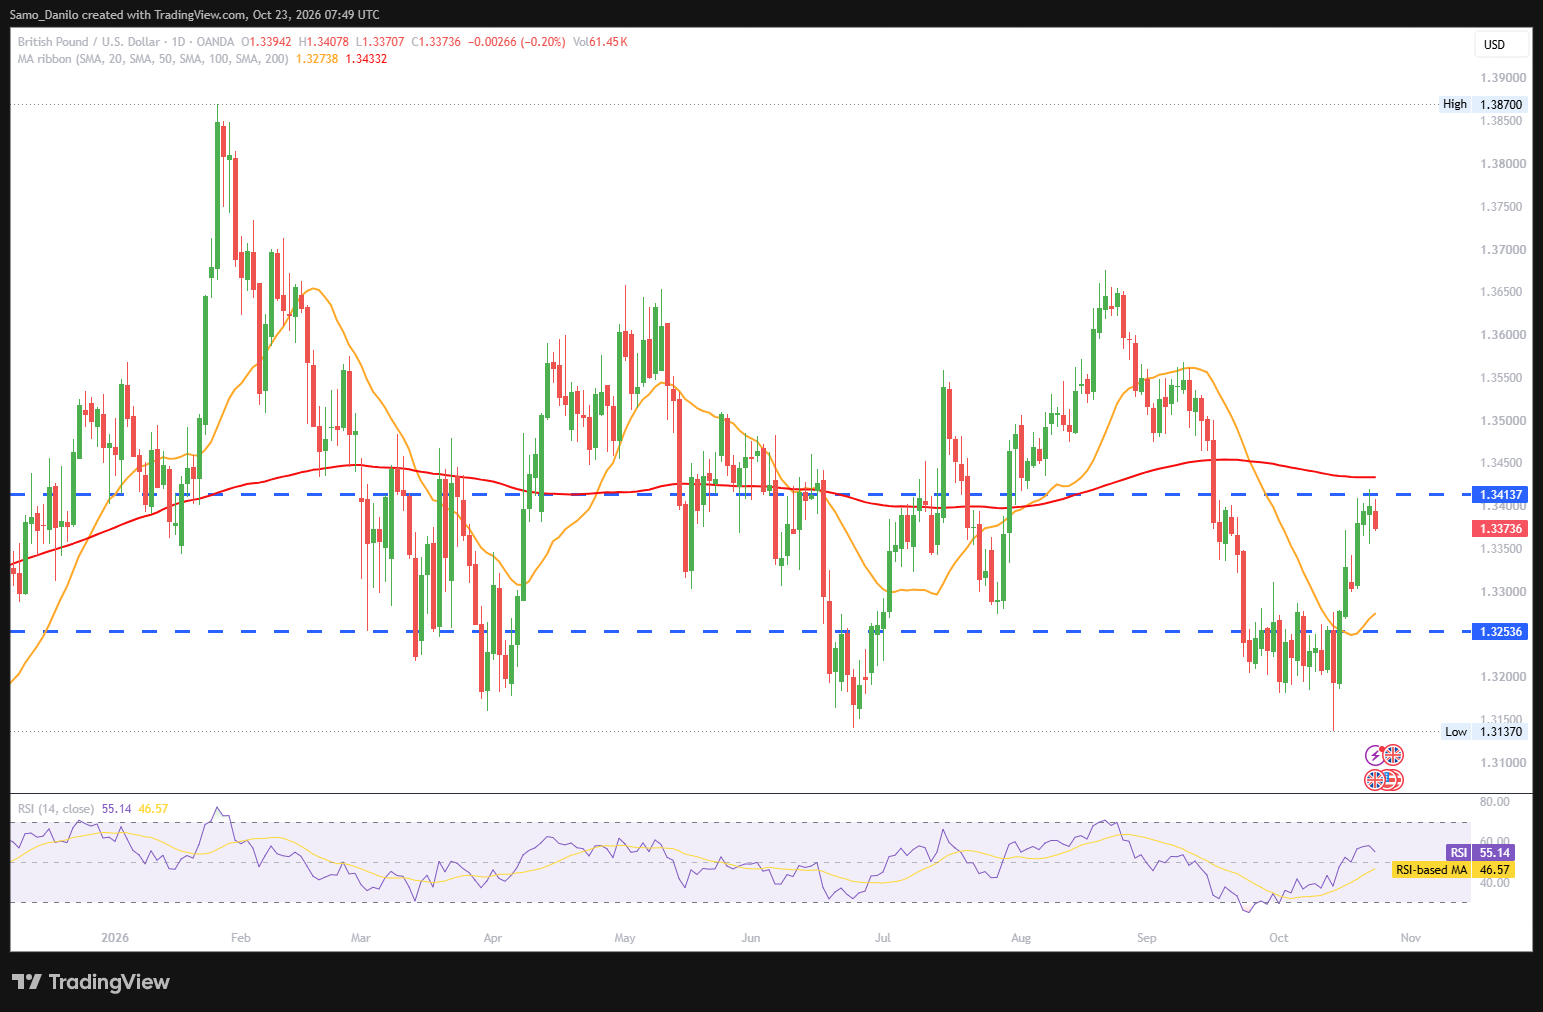
| SMA (20) | Falling | | |
| RSI (14) | Slightly Rising |  |
|
| MACD (12, 26, 9) | Slightly Rising | |
Closing statement: GBP/USD is hovering around 1.3390 as disappointing UK retail sales and sharply weaker consumer confidence are offset by expectations of further monetary tightening from the Bank of England. Persistent inflation may support sterling if markets anticipate a rate hike on November 5, but weakening domestic demand remains a downside risk. The upcoming US flash PMIs could determine the pair’s immediate direction, with stronger US activity potentially strengthening the dollar and limiting GBP/USD gains.
XAUUSD
- XAU/USD Price: Gold (XAU/USD) is showing some resilience below the psychological $4,000 level, rebounding from a three-month low reached earlier on Friday.
- Jobless claims: US initial jobless claims came in at 194,000, below the expected 200,000, while continuing claims reached 1.73 million, slightly above the forecast of 1.71 million.
- Fed rate: Traders are still pricing in approximately an 80% probability that the Federal Reserve will raise borrowing costs again at its December policy meeting.
- Fed's Warsh: Recent remarks from Federal Reserve Chair Warsh indicated that elevated inflationary pressures remain a key concern for the central bank.
- US Dollar: Gold has continued to decline despite the US dollar falling to a three-week low, as investors sell the currency amid concerns surrounding the AI trade and debt-funded investment in AI infrastructure. The lack of stronger safe-haven demand for gold suggests that interest-rate expectations are currently outweighing the support typically provided by dollar weakness.
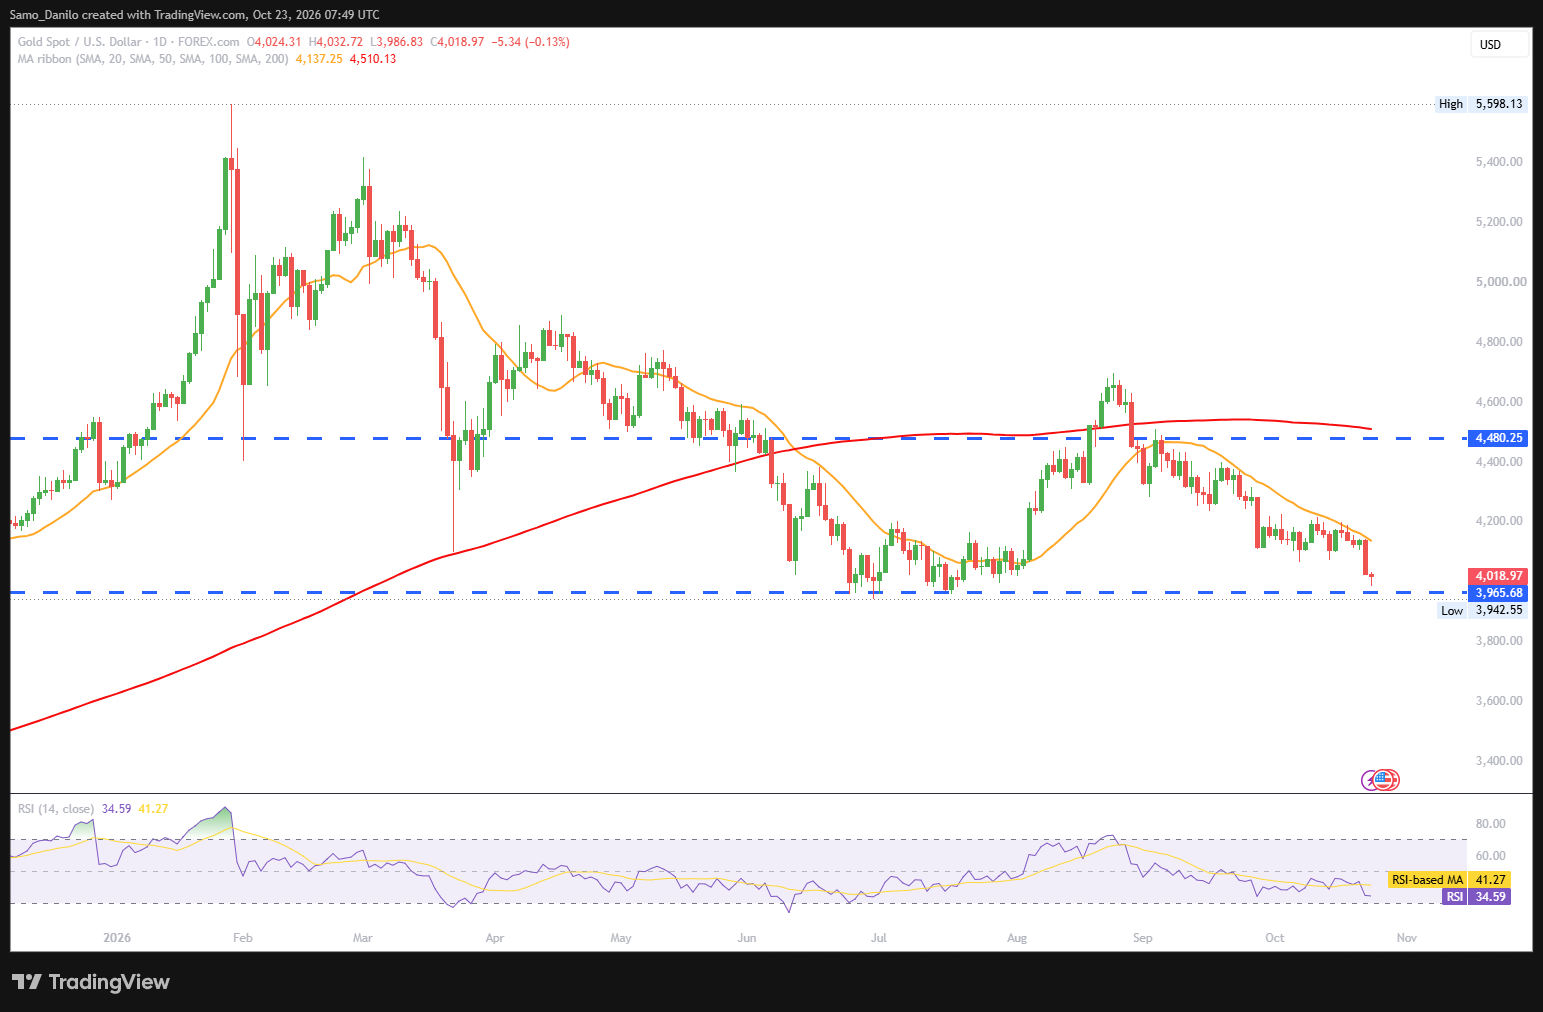
| SMA (20) | Slightly Falling | |
| RSI (14) | Slightly Falling | |
| MACD (12, 26, 9) | Slightly Falling | |
Closing statement: Gold is attempting to recover below $4,000 after reaching a three-month low, but the broader outlook remains under pressure. Resilient initial jobless claims, persistent inflation concerns and expectations of a December Fed rate hike are weighing on the precious metal, even as the US dollar weakens. In the near term, gold’s direction will likely depend on shifts in interest-rate expectations and safe-haven demand, with a sustained recovery requiring a meaningful easing of monetary-policy pressures or renewed buying interest.
CRUDE OIL
- Crude Oil Price: Crude oil prices remain near the one-month peak reached on Tuesday, with WTI trading around $102.20 amid escalating conflict in the Middle East.
- Refining capacity: US President Donald Trump announced plans to release $150 million to increase domestic refining capacity, using the Defense Production Act to support the production of diesel and gasoline.
- Saudi Aramco: Saudi Aramco has reportedly instructed employees to evacuate its headquarters in Dhahran and work remotely, according to press reports.
- Regional escalation: Iran’s Islamic Revolutionary Guard Corps (IRGC) warned that renewed US attacks could prompt Tehran to invade neighbouring countries and target bases used in US military operations as part of a new offensive strategy.
- Military action: Reports that the United States and Israel have drawn up plans for a short but intense military campaign against Iran following the US midterm elections continue to keep geopolitical risks elevated.
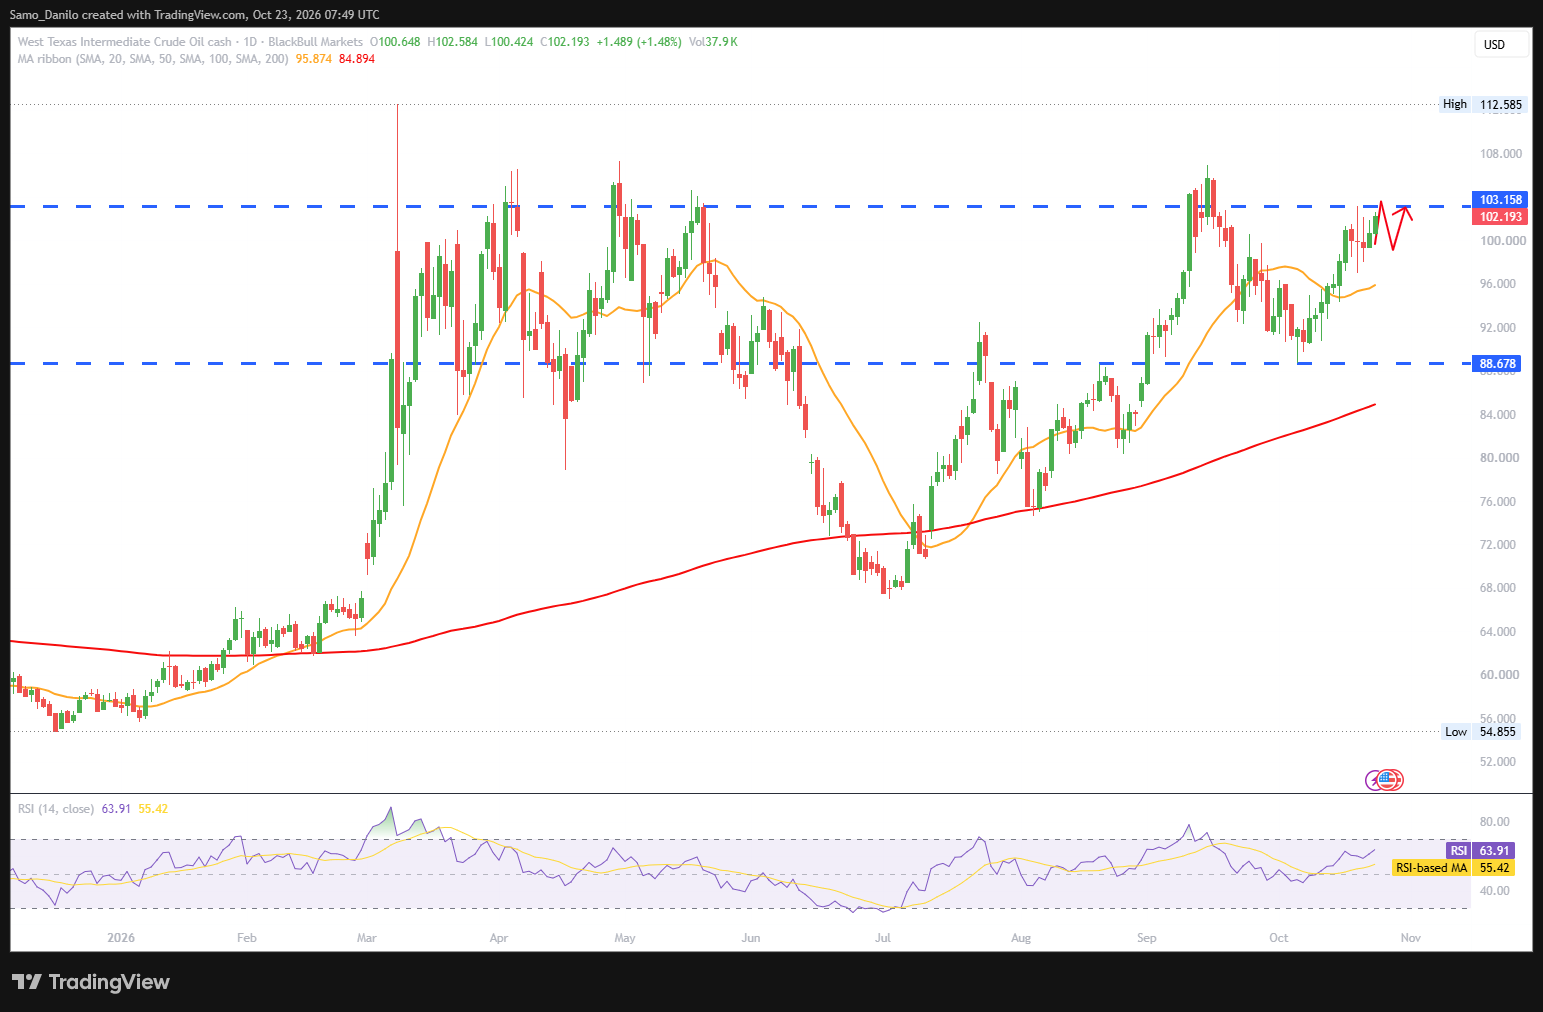
| SMA (20) | Slightly Rising | |
|
| RSI (14) | Rising | | |
| MACD (12, 26, 9) | Slightly Rising | |
Closing statement: WTI is trading around $102.20, supported by escalating Middle East tensions and growing concerns over potential disruptions to regional oil supplies. In the near term, crude prices are likely to remain highly sensitive to developments in the region, with further escalation potentially driving prices higher and signs of de-escalation increasing the risk of a pullback.
DAX
- DAX 40 Price: The DAX 40 is trading lower at around 25,200 points on Friday morning.
- Finance Minister: German Finance Minister Lars Klingbeil said the government would not gain any additional fiscal room for manoeuvre in 2027, while federal tax revenue projections for the current fiscal year are €3 billion below the May forecast.
- Consumer confidence: Eurozone consumer confidence declined more than expected in October to -17.9, compared with a consensus forecast of -17.0 and the previous reading of -16.8.
- Bond spread: The spread between French and German 10-year government bond yields is testing 175 basis points, highlighting persistent concerns over France’s fiscal outlook relative to Germany’s.
- Corporate lending: Deutsche Bank reportedly intends to strengthen its position in lending to German companies and attract clients from Commerzbank, taking advantage of uncertainty surrounding UniCredit’s offer to take control of the lender, according to Milano Finanza.
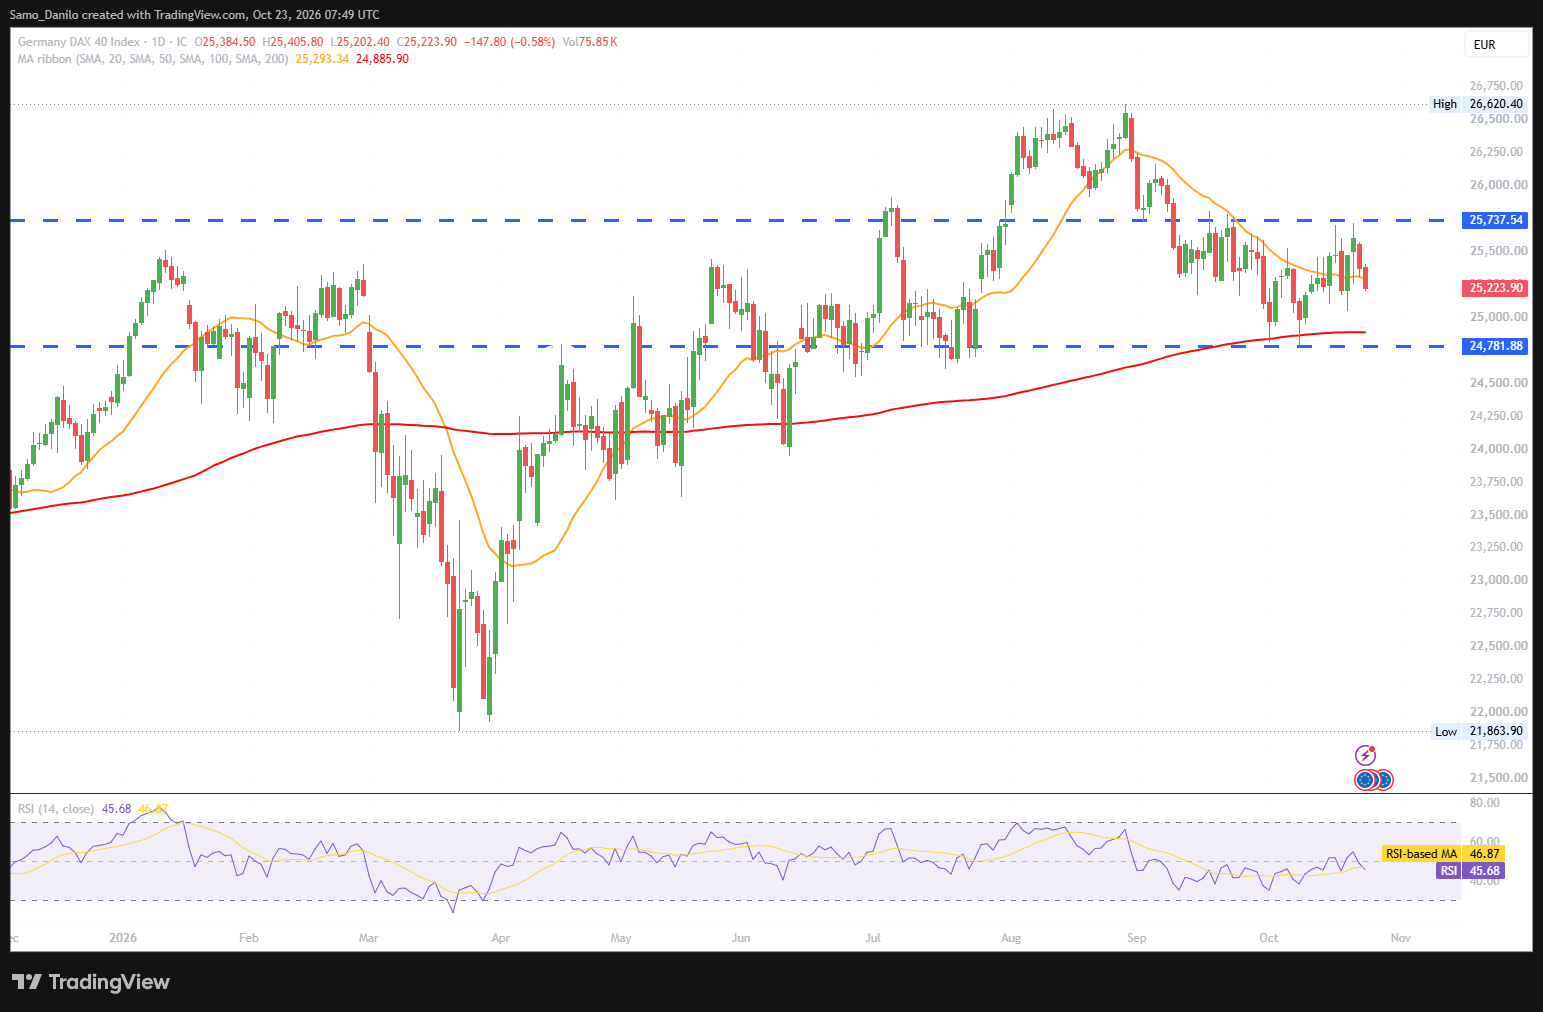
| SMA (20) | Slightly Falling | |
| RSI (14) | Slightly Falling | |
| MACD (12, 26, 9) | Slightly Falling | |
Closing statement: The DAX 40 is trading lower near 25,200 points as concerns over Germany’s limited fiscal flexibility and weakening eurozone consumer confidence weigh on the outlook. In the near term, the index may remain under pressure unless economic sentiment improves or corporate developments provide a stronger catalyst for buying.