EURUSD
- EUR/USD Price: The EUR/USD pair is trading in positive territory near 1.1220 during early European trading on Monday.
- PMI data: The eurozone flash Composite PMI declined to 51.9 in October, missing expectations of 52.7 and falling from 53.1 in September.
- France’s rating: Moody’s kept France’s credit rating unchanged at Aa3 with a negative outlook late on Friday, despite widespread market expectations of a downgrade.
- Danish data: Business sentiment in Denmark fell to 104.5 in October from 107.1 in September, marking its lowest level in four months. Despite the decline, the indicator remains above its historical average of 100, suggesting that business confidence is still consistent with expansion, although momentum has weakened.
- ECB rate: Investors are awaiting Thursday’s European Central Bank policy meeting, with markets broadly expecting interest rates to remain unchanged.
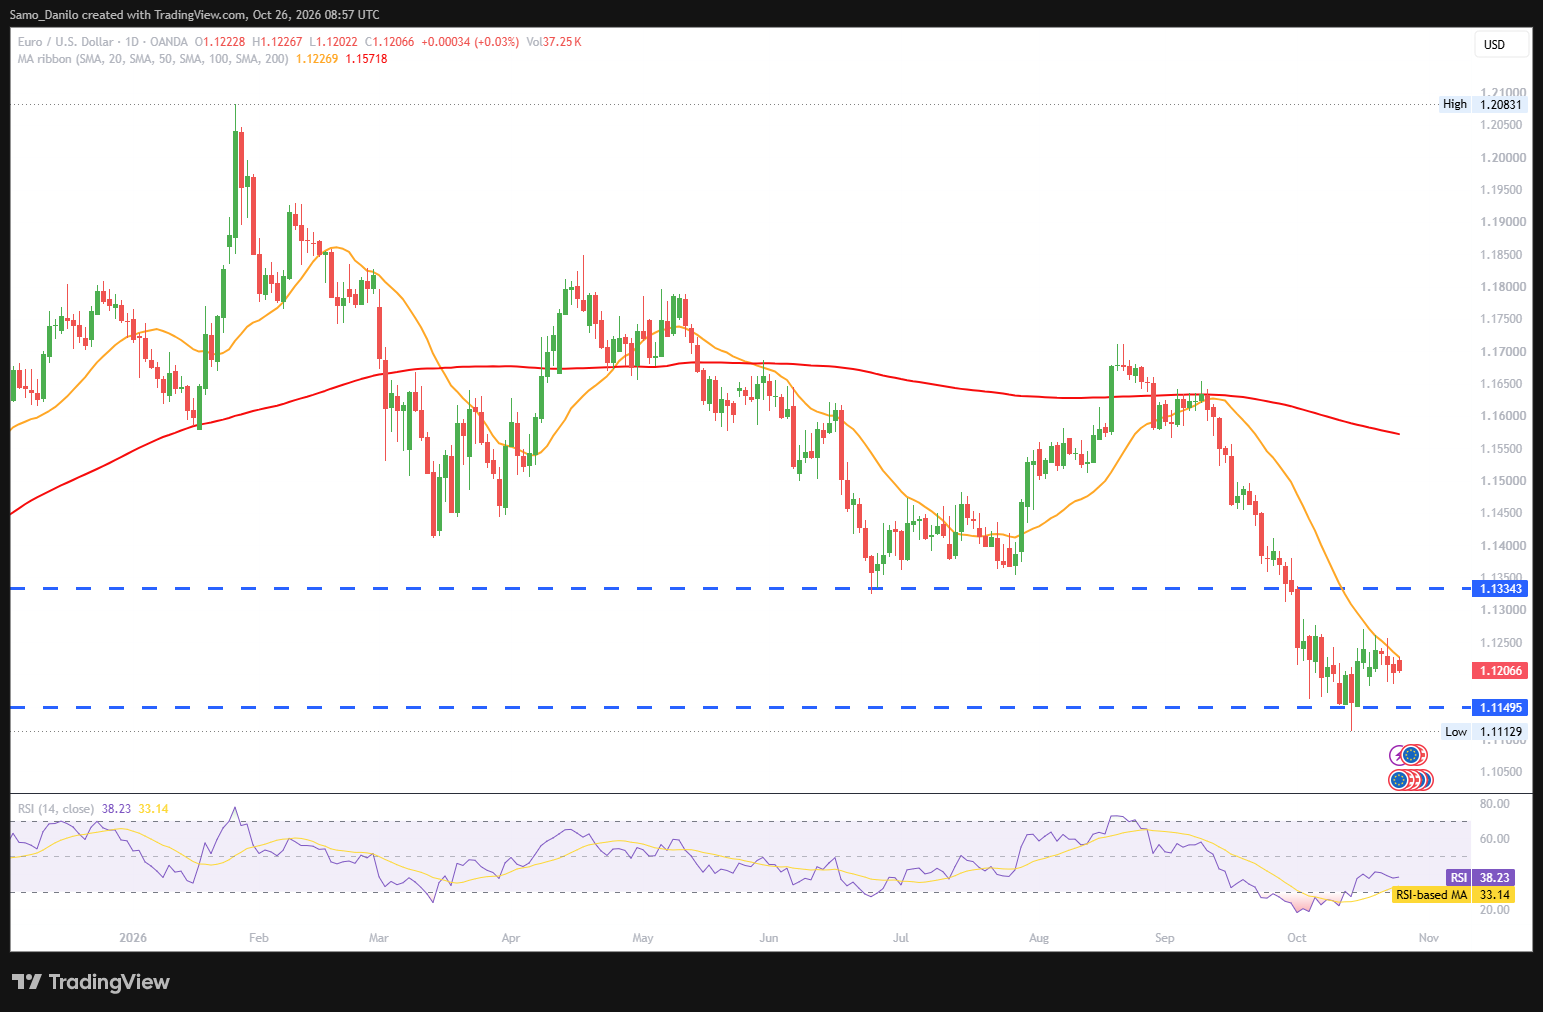
| SMA (20) | Falling |  | |
| RSI (14) | Slightly Falling | |
|
| MACD (12, 26, 9) | Slightly Falling | |
Closing statement: EUR/USD is holding near 1.1220 as markets balance continued eurozone economic expansion against signs of weakening momentum. Moody’s decision to maintain France’s credit rating offers some relief, while expectations of unchanged ECB rates may limit immediate volatility ahead of Thursday’s meeting. In the near term, the pair’s direction will likely depend on the ECB’s policy guidance and whether incoming economic indicators reinforce concerns about a slowdown or demonstrate greater resilience.
GBPUSD
- GBP/USD Price: The British Pound has given back its early gains and is trading lower against the US Dollar at around 1.3350 during Monday’s European session.
- Business activity: The UK flash Composite PMI increased to 53.1 in October from 52.0 in September, reflecting stronger activity across both major sectors. The Services PMI rose to 53.1 from 52.1, while the Manufacturing PMI improved to 52.8 from 51.9, indicating broader economic resilience and potentially providing support for sterling.
- UK Budget: The UK’s 2027 budget, scheduled for Wednesday, is expected to attract significant attention ahead of the Bank of England’s November policy meeting.
- UK government: The UK Prime Minister’s Office announced that the government will allocate an additional £432 million to help tackle homelessness.
- UK pensions: According to The Times, Chancellor of the Exchequer John Healey is expected to announce a 3.9% increase in the full state pension. The proposed rise could add to government spending commitments and may become relevant to discussions surrounding the UK’s fiscal outlook and upcoming budget.
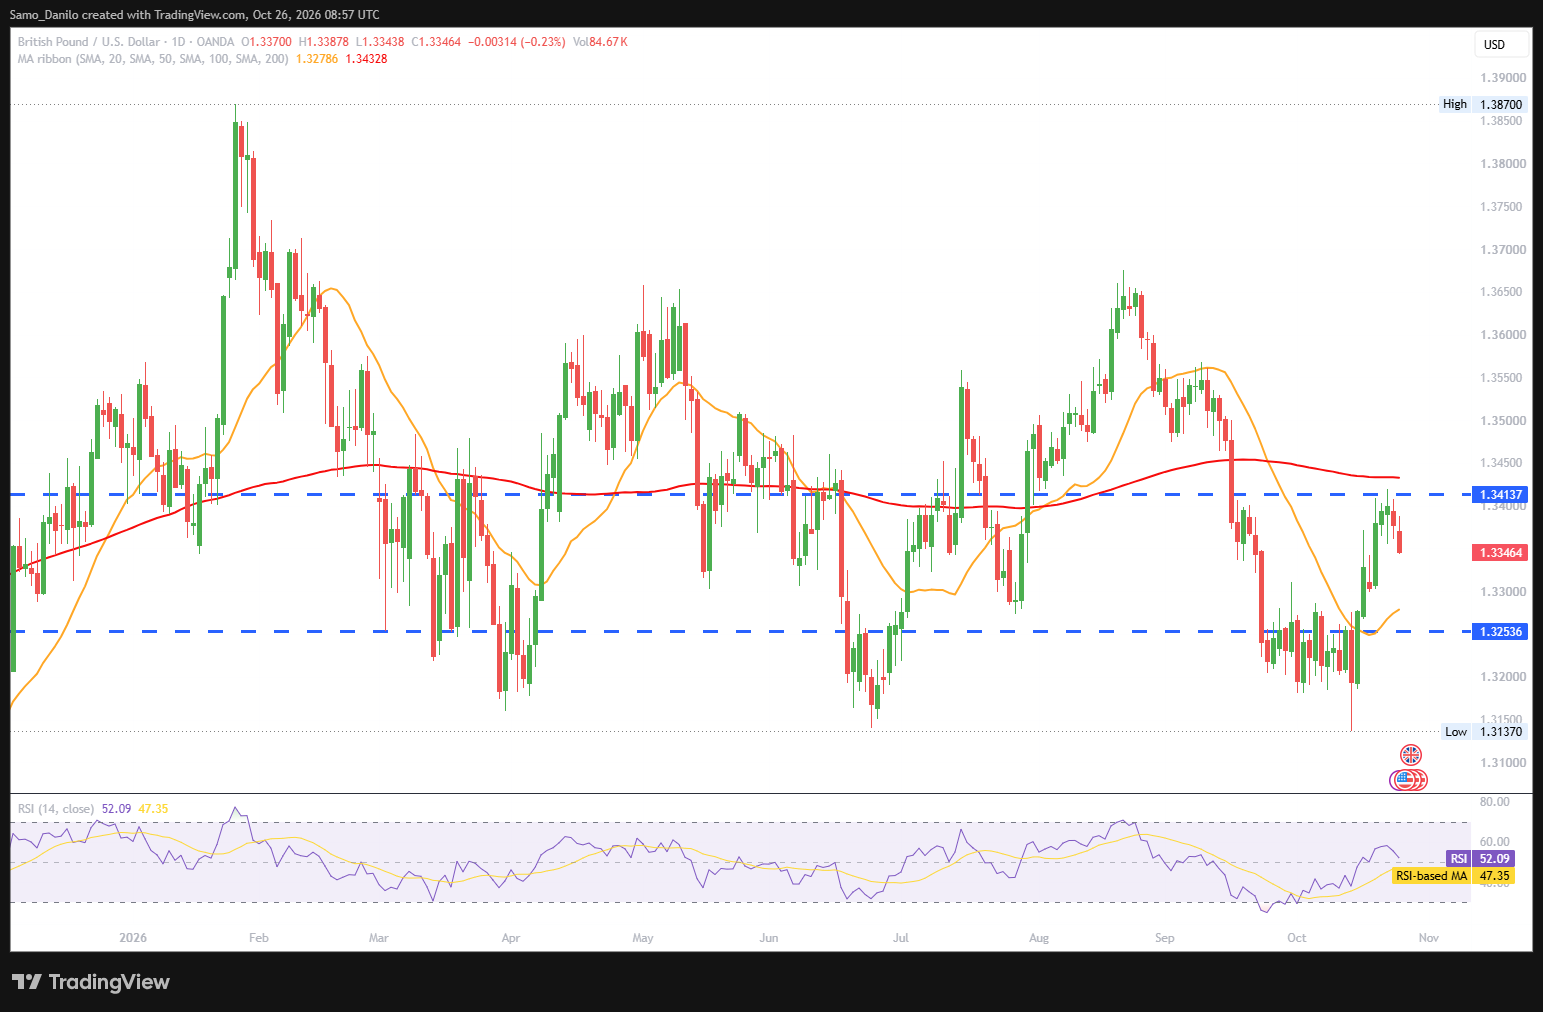
| SMA (20) | Falling | | |
| RSI (14) | Slightly Rising |  |
|
| MACD (12, 26, 9) | Slightly Rising | |
Closing statement: GBP/USD is trading lower near 1.3350 despite encouraging UK PMI figures, which point to stronger economic momentum and could reinforce expectations of tighter Bank of England policy. Stronger growth and persistent inflation could support sterling, although fiscal concerns and broader US dollar demand may limit further gains.
XAUUSD
- XAU/USD Price: Gold (XAU/USD) is maintaining modest intraday gains above the psychological $4,000 mark during early European trading on Monday.
- US PMIs: The US S&P Global flash Composite PMI edged lower to 57.6 in October from 58.4 in September, although overall business activity remained firmly in expansion territory. Manufacturing activity performed better than expected, reaching 56.0, suggesting continued resilience in the US economy that could support expectations of a restrictive Federal Reserve policy.
- Fed rate: According to the CME FedWatch Tool, markets are pricing in a 90.6% probability that the Federal Reserve will leave interest rates unchanged at its upcoming October meeting on Wednesday. However, traders continue to assign a 79.4% probability to a rate hike in December, with expectations of tighter monetary policy potentially limiting gold’s recovery by increasing the opportunity cost of holding non-yielding assets.
- Chinese data: China’s September industrial profit figures are due for release, following a slowdown in annual profit growth to 4.2% in August. However, improving manufacturing PMI data and higher producer price inflation point to a potential recovery in September, particularly in the raw materials and semiconductor sectors, which could influence expectations for Chinese economic demand and gold consumption.
- Brazil’s election: Luiz Inácio Lula da Silva secured a historic fourth presidential term in Brazil’s runoff election on Sunday, winning 51.76% of the vote against Flávio Bolsonaro. Bolsonaro has refused to concede and announced plans to challenge the result legally, creating additional political uncertainty in Latin America.
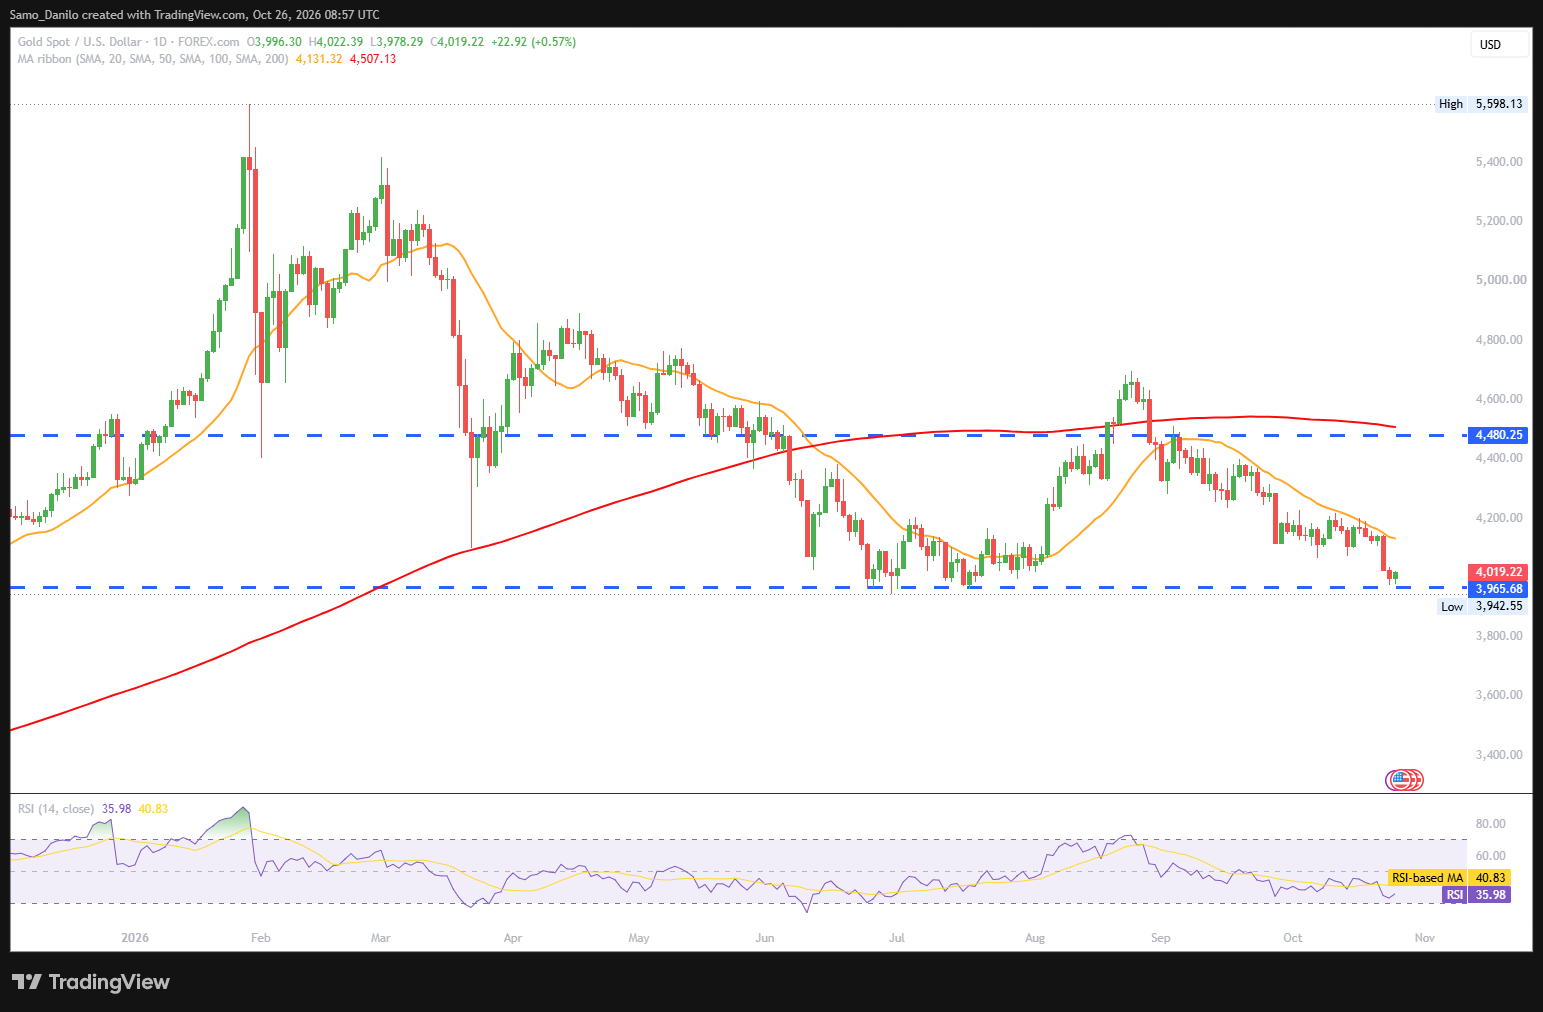
| SMA (20) | Slightly Falling | |
|
| RSI (14) | Falling | | |
| MACD (12, 26, 9) | Slightly Falling | |
Closing statement: Gold is holding above $4,000 but continues to struggle to attract strong buying interest following its recent three-month low. Strong US economic activity and expectations of a December Fed rate hike remain significant headwinds, while the anticipated October rate hold could offer some short-term relief. A sustained recovery will likely require stronger safe-haven demand or a meaningful shift toward a less restrictive US monetary policy outlook.
CRUDE OIL
- Crude Oil Price: Crude oil is trading lower at around $102.30 during Monday’s European session.
- Diplomatic efforts: Qatari mediators travelled to Tehran on Sunday as part of an initiative to de-escalate regional tensions in coordination with the United States.
- Houthi attacks: The Houthis reportedly claimed responsibility for attacks targeting several Saudi airports, an Aramco facility in Yanbu, the East-West pipeline and associated pumping stations.
- IEA outlook: International Energy Agency Chief Fatih Birol said he does not see a credible pathway for energy markets to return to their pre-Iran war levels in 2027.
- Regional meetings: Senior officials from Saudi Arabia, Turkey and Pakistan are expected to meet Iranian representatives in Tehran on Monday, October 26, to discuss regional coordination under the Mecca Pact.
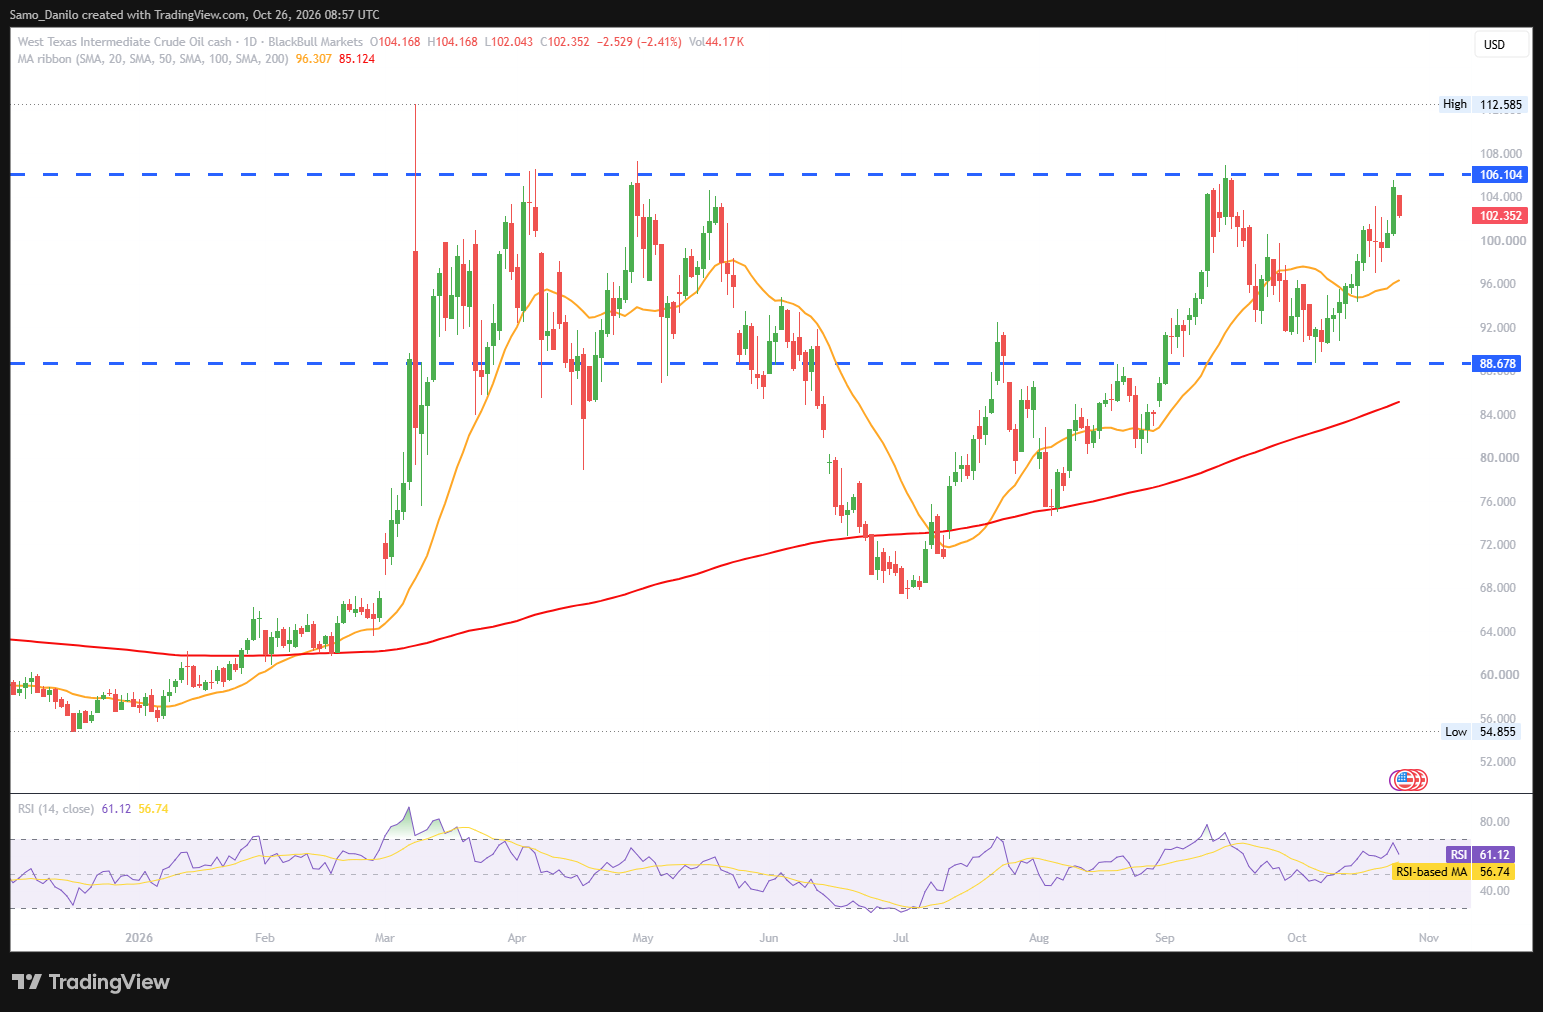
| SMA (20) | Slightly Rising | |
|
| RSI (14) | Rising | | |
| MACD (12, 26, 9) | Slightly Rising | |
Closing statement: WTI is trading lower near $102.30 as diplomatic initiatives involving Qatar, the United States and regional powers raise hopes of easing tensions with Iran. In the near term, crude oil is likely to remain highly sensitive to developments in Tehran and the security of Saudi energy infrastructure, with diplomatic progress potentially driving prices lower while further attacks could trigger renewed gains.
DAX
- DAX 40 Price: The DAX 40 is trading higher at around 25,375 points during Monday morning's session.
- Business activity: Germany's Ifo business climate indicator for October is in focus, following Friday's flash PMI data, which pointed to decent growth momentum at the start of the fourth quarter. However, the composite PMI came in slightly below expectations as weaker services activity offset a positive surprise in manufacturing, suggesting that the recovery remains uneven across sectors.
- Cruise missiles: Germany is reportedly preparing to purchase cruise missiles developed in Ukraine, highlighting growing defence cooperation between the two countries.
- Audi plans: Audi is reportedly planning to invest approximately $4 billion in its first US manufacturing plant, which is expected to be located in Georgia. The investment would represent a significant expansion of the company's US production footprint, although its broader implications for Volkswagen Group's operations and financial performance will depend on the project's implementation.
- Moody's outlook: Moody's expects France's budget deficit to reach 5.2% of GDP next year, slightly above the government's 5% target. Although this would represent an improvement from the 5.4% deficit expected by the government for this year, persistent fiscal pressures could continue to weigh on investor confidence and broader European market sentiment.
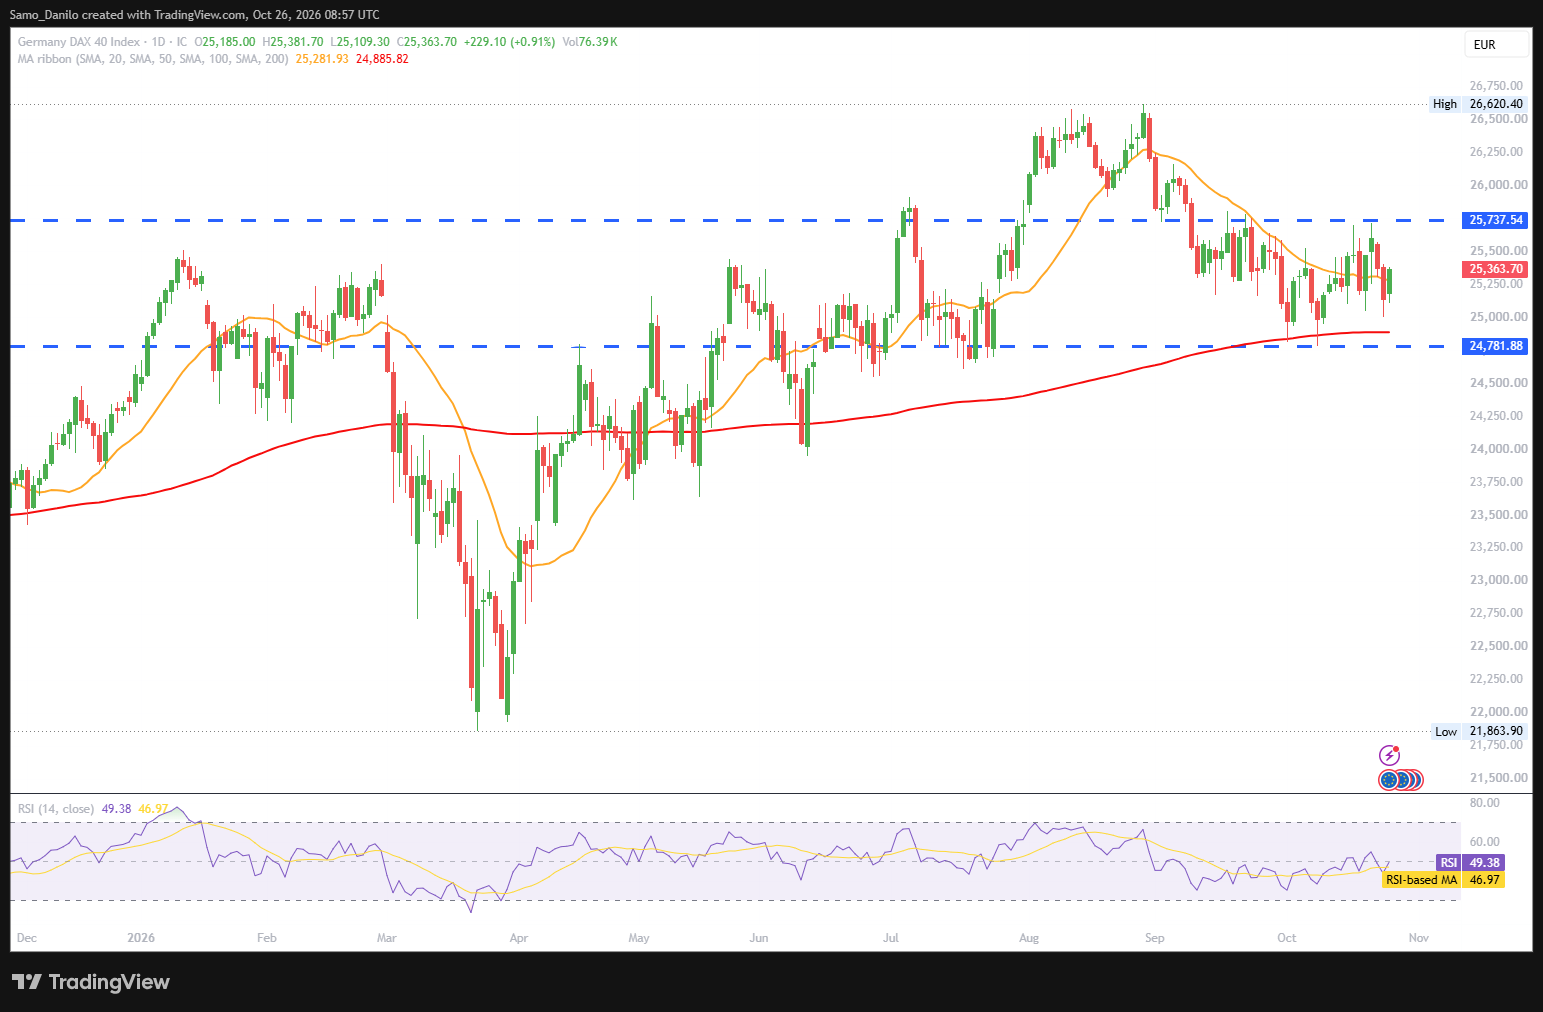
| SMA (20) | Slightly Falling | |
| RSI (14) | Slightly Falling | |
| MACD (12, 26, 9) | Slightly Falling | |
Closing statement: The DAX 40 is trading higher this morning, supported by relatively solid German growth momentum and positive manufacturing signals. The index's near-term direction will likely depend on incoming German data and broader European investor sentiment.